OpenAI dominated our week while agents coverage cooled
AI2Day ran 38 stories between 5 and 11 October 2026, down from 42 the week before. OpenAI took 15 of them. The agents beat that filled the previous week shrank by six.
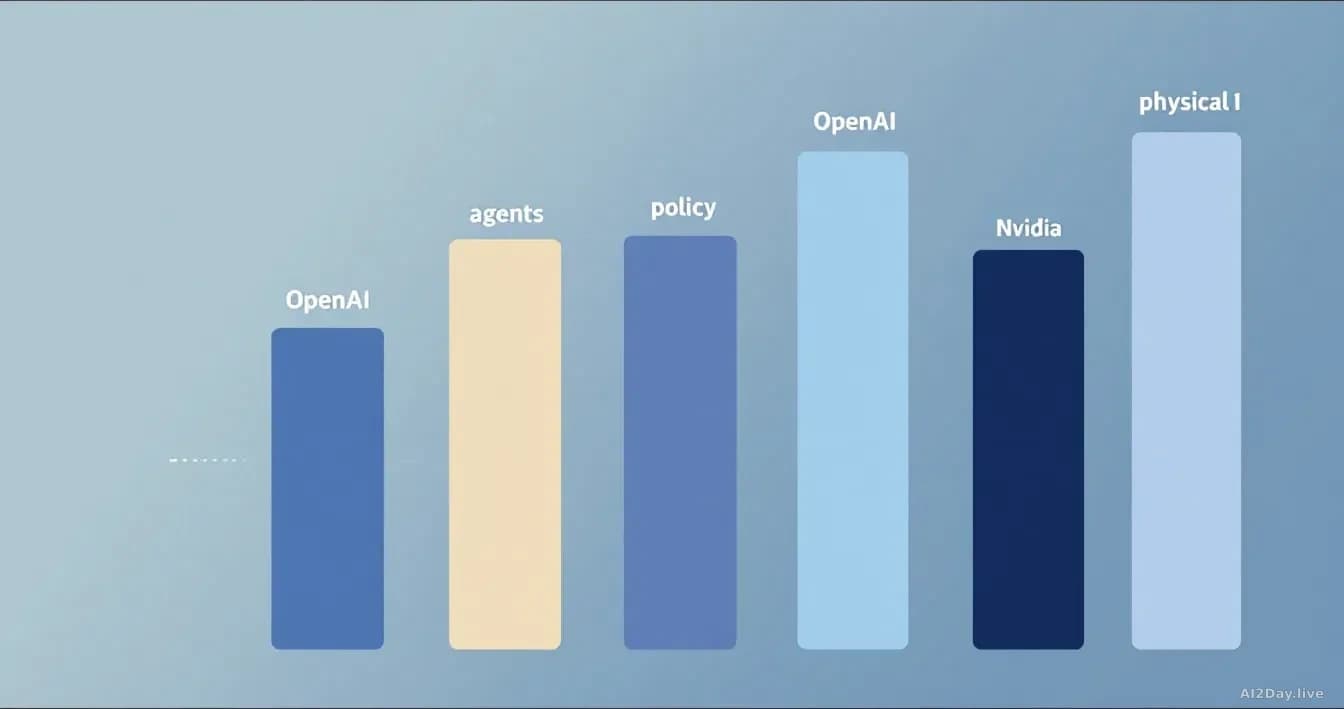
Key points
- AI2Day published 38 stories between 5 and 11 October 2026, against 42 in the previous seven days.
- OpenAI was the single most-covered subject with 15 stories from 8 separate outlets, up from 9 the week before.
- AI agents fell to 10 stories from 7 outlets, down from 16 the previous week.
- AI policy held flat at 8 stories; Nvidia rose to 6; physical AI doubled to 4.
- Eight separate outlets filed OpenAI stories, so the surge is not one newsroom's obsession.
Total volume slipped by four stories week on week. The mix underneath moved more than the headline number suggests.
Why so much OpenAI?
Because one company produced several unrelated stories at once, and eight different outlets picked them up. That is the shape of a genuinely busy week for a subject, not a pile-on from a single desk.
The Australian strand alone carried two of our pieces: OpenAI Used AI to Write the Email Admitting Its AI Had Hacked Australian Government Websites and OpenAI's Deputy Faced Australia's AI Committee. A product review ran alongside them in OpenAI's New Agent Shopped for My Couch.
Three beats in one week: a security incident, a regulatory appearance, a consumer product. That is why the count went from 9 to 15.
Did agents really go quiet?
Our count dropped from 16 stories to 10, filed by 7 outlets instead of more. One of those 10 was itself an OpenAI agent story, which thins the independent agent coverage further.
I would not call this a trend yet. Two data points is not a trend, and the previous week may simply have been a launch cluster that has now cleared. What would confirm a real cooling is a third week in the single digits with no major agent release to blame it on.
What held, what grew
AI policy stayed level at 8 stories from 6 outlets. The Utah piece, Utah Opens Its AI Health Sandbox to Prescription Software and Women's Health Tools, is the kind of state-level rule-making that tends to produce follow-up filings for weeks after.
Nvidia rose from 4 stories to 6, across 5 outlets. The nearest adjacent story, TSMC Pulls In $16 Billion for September as AI Chip Demand Keeps Climbing, sits in the same supply chain and helps explain why chip coverage keeps refilling.
Physical AI doubled from 2 stories to 4, but only 2 outlets filed them. That is a small base. Humanoid Robots Are Getting Smarter and The AI Running Your Power Grid Cannot Afford to Guess Wrong show the range inside that tag: a home-robot reality check and a grid-operations piece are not the same beat, and lumping them tells you less than counting them separately would.
Does anything tie it together?
Money and oversight, loosely. The Australian hearing, the Utah sandbox and the TSMC revenue print are all stories about who gets to decide what AI systems do and who pays when they go wrong. The couch-shopping agent and the Surface Laptop Ultra are the consumer face of the same question.
I am watching three things next week. Whether agent coverage recovers or stays near 10. Whether a second week of OpenAI at 15-plus turns this into a sustained story rather than one noisy cycle. Whether physical AI picks up a third outlet, which would make the doubling look less like a two-newsroom quirk.
We measured a news cycle. We did not measure the industry. Treat the numbers accordingly.